Australia · rules version 15 October 2026
Are you better or worse off under the 2027 tax changes?
An Investor Impact Report for one property. Illustrated tax under the old 50% discount and under the new rules, across growth rates, plus negative gearing, the 30% minimum tax, and whether a 30 June 2027 valuation is worth pricing. General information — then take it to your registered tax agent.
$39 for one property · $99 for up to five · the free check does not call a valuation model
Free · no property data call
A 60-second check
Purchase year and price, your own estimate of the 30 June 2027 value, a growth rate, and an income band. Nothing here calls a valuation model.
What the paid report adds
- A modelled value at 30 June 2027, with the suburb's recent growth, from HtAG Analytics. Not a valuation.
- Illustrated tax at several growth rates and sale years, and the growth rate where the two rules cross.
- Negative gearing from the date and dwelling you assert, including the 12 May 2026, 7:30pm cutoff and carry-forward.
- Whether the 30% minimum tax shows up in the sale year you described.
- The existing valuation test, framed as an option you can price in 2027.
- A dated checklist and an accountant appendix. Rules version on the cover. Draft law marked.
High growth usually illustrates more tax under the new rules. Low growth often illustrates less. The rough crossover is about twice inflation. Pre-2027 gains keep the 50% discount either way, so 30 June 2027 is a modelling date, not a deadline to sell.
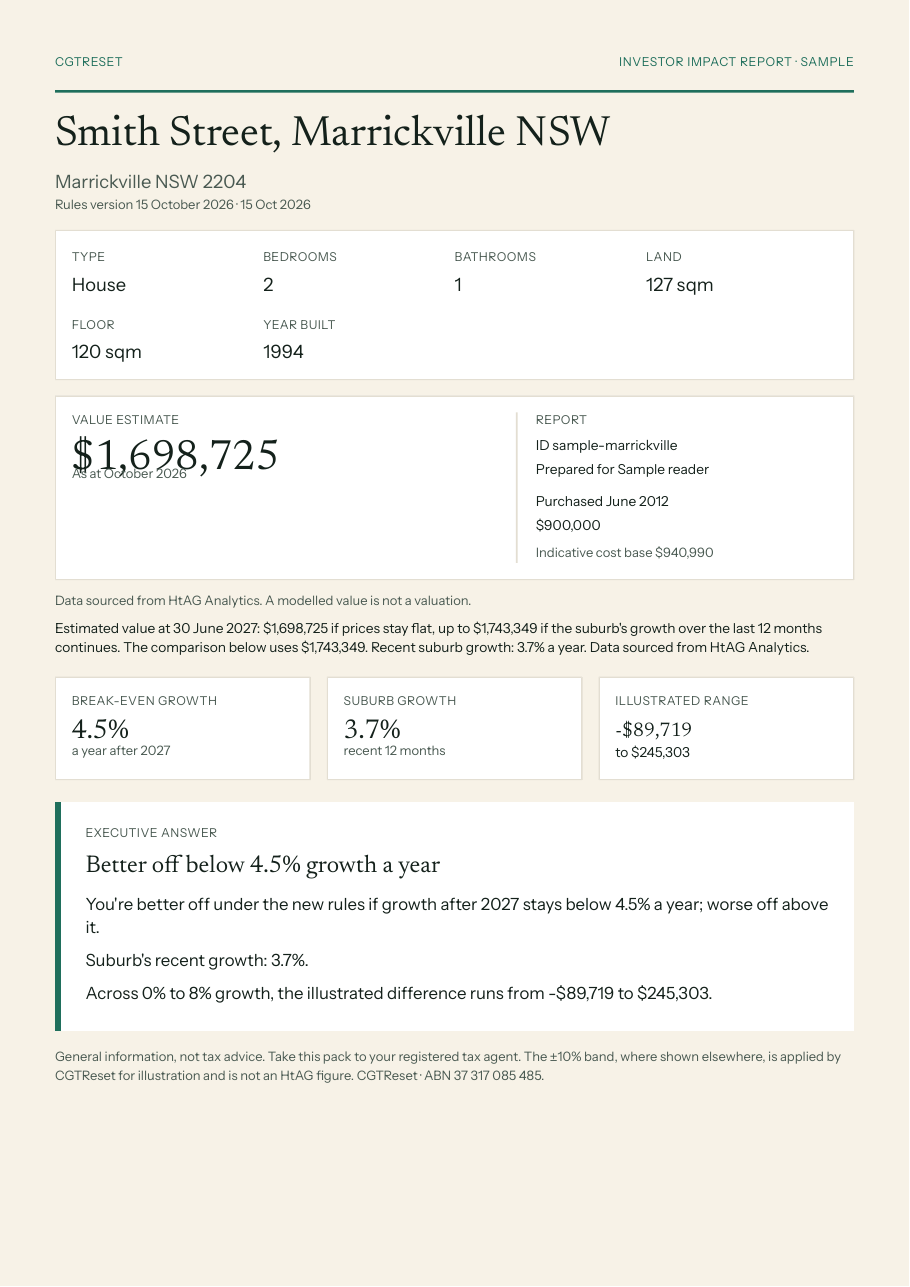 Open the sample report
$39
One property. Modelled value, scenarios, checklist, PDF.
Free
The 60-second check. Your numbers only. Three value rows, not a single answer.
One property · $39
Investor Impact Report
We check the address can be modelled before Stripe. The report adds a modelled 30 June 2027 value, suburb history, comparable-sales range, the valuation option, and a PDF your tax agent can read.
The income band is stored as one illustrative figure, not your assessed taxable income. Month and year are stored as the first of the month and printed as “June 2016”.
Before you pay
This is general information and arithmetic on the facts you enter. It is not a tax agent service, not financial advice, and not a valuation. A trust, company or SMSF is flagged and not given an individual's headline as if it were that entity's tax.
The apportioning formula is still an exposure draft. The Tax Reform No. 3 Bill, introduced on 14 October 2026, is not yet law. Reports are stamped 15 October 2026 so you can see which version you were shown.
We charge only after a property can be modelled. If we take payment and cannot deliver the report, the fee is refunded. There is no valuer panel.